What the Texas franchise tax actually is
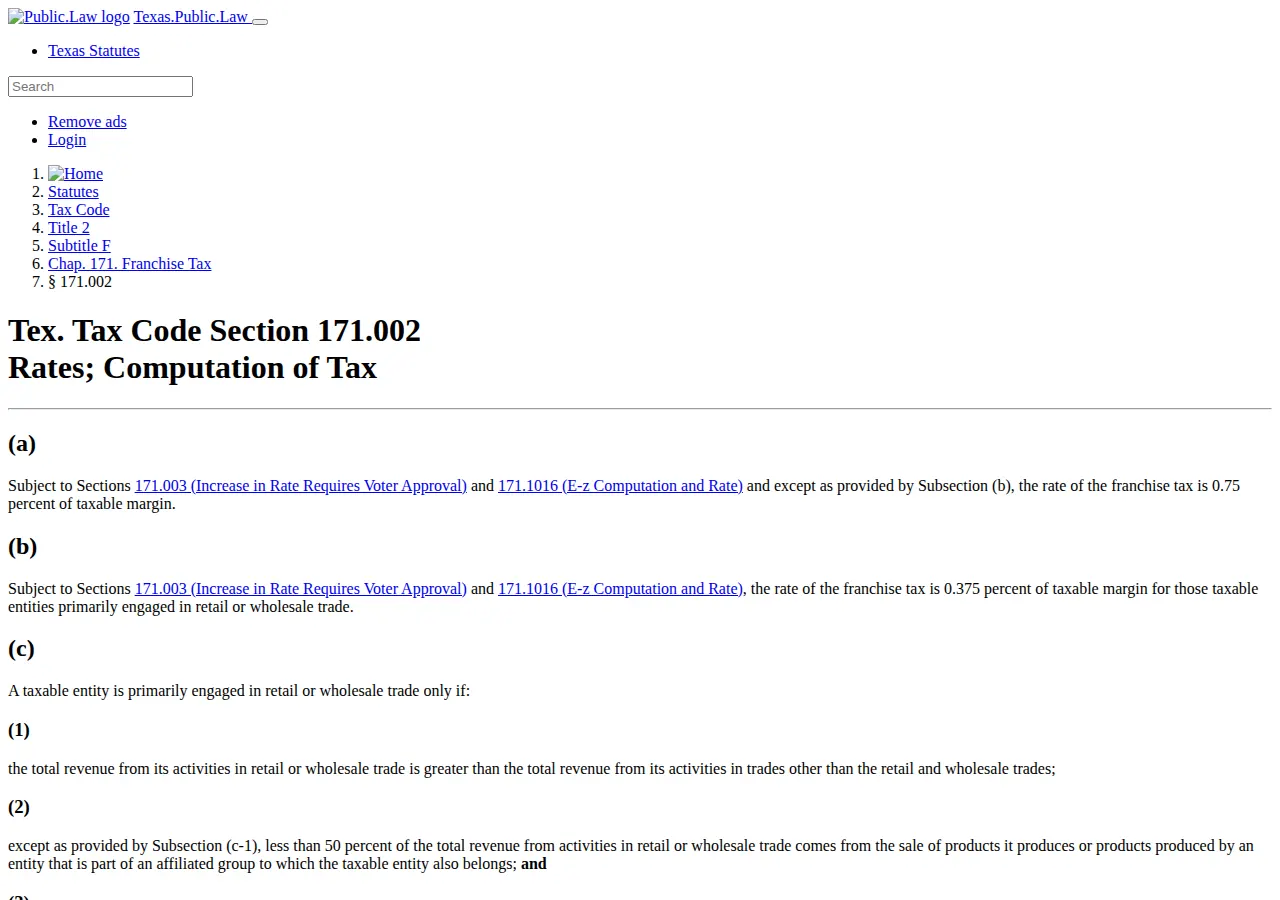
The Texas franchise tax is a privilege tax imposed on each taxable entity formed or organized in Texas or doing business in Texas, under Texas Tax Code Chapter 171. It is not an income tax. The state taxes margin — total revenue minus a deduction the entity elects — at 0.75 percent, or 0.375 percent for entities primarily engaged in retail or wholesale trade, under Tex. Tax Code § 171.002. Because the base is margin, a business can post a federal loss and still owe Texas money.
The net is wide. Every corporation, LLC — including a single-member LLC and a series LLC — bank, S corporation, partnership, trust, and joint venture formed in Texas or doing business here is a taxable entity, per Publication 98-806. The exclusions are narrow: sole proprietorships (except single-member LLCs, which are taxable), general partnerships owned entirely by natural persons (except LLPs), and entities exempt under Chapter 171, Subchapter B.
That last line matters. A founder who runs the business as a sole proprietorship owes no franchise tax; the day the same business becomes a single-member LLC — usually for liability protection — it enters the franchise tax system.
The rate table: what 2026 and 2027 actually cost
The Comptroller publishes rates, thresholds, and deduction limits by report year. For 2026 and 2027 the no-tax-due threshold is $2,650,000, the rates are 0.375 percent for retail or wholesale and 0.75 percent for everyone else, the compensation deduction limit is $480,000 per person, and the EZ rate is 0.331 percent on total revenue up to $20 million. For 2024 and 2025 the threshold was $2,470,000 and the compensation limit $450,000. The threshold jumped from $1,230,000 in 2022 and 2023 — a doubling that took thousands of small entities out of the tax entirely.
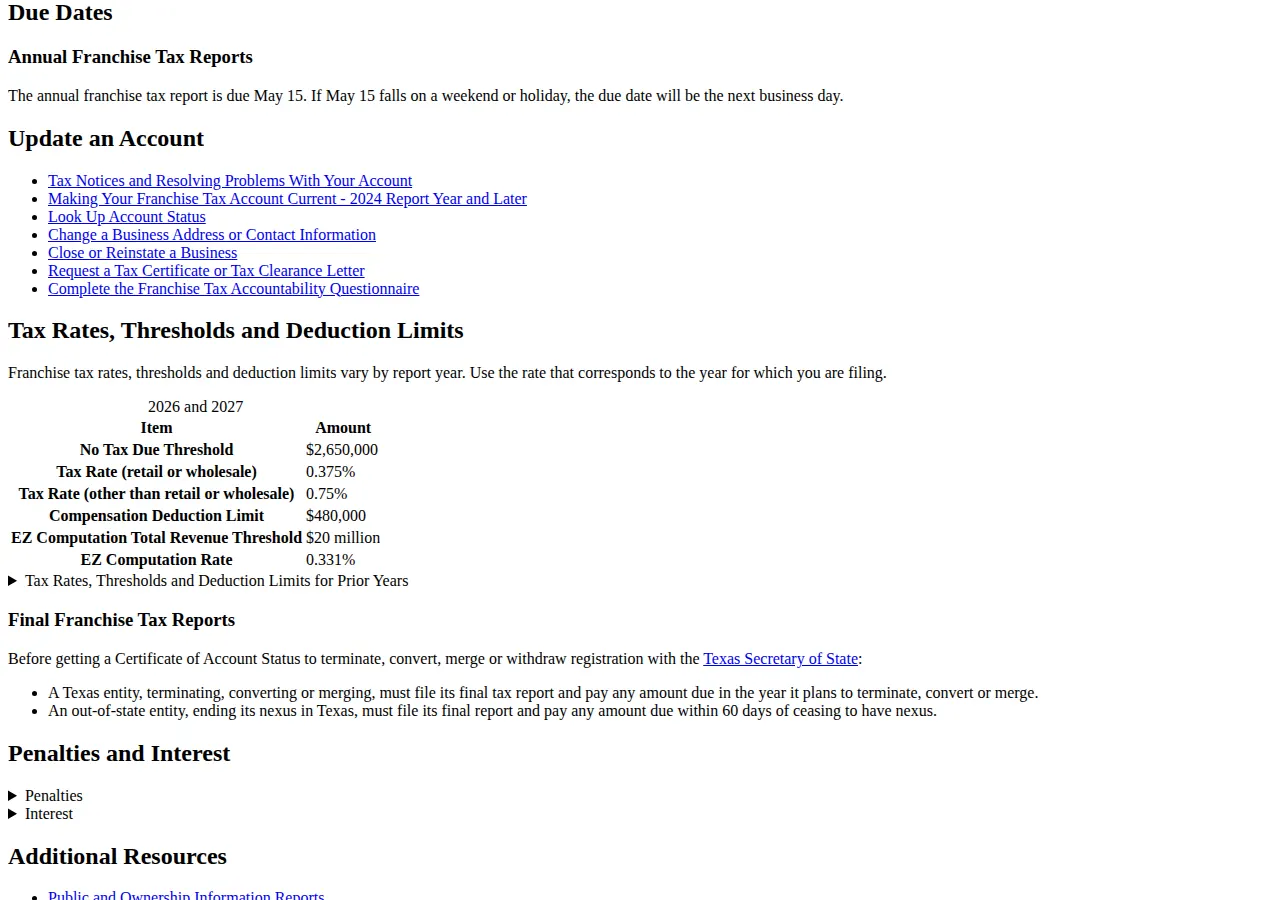
Note two features: the threshold is measured on total revenue from the entire business, not Texas revenue alone — and it is a cliff, not a phase-out. At $2,650,001 the tax applies to the whole taxable margin, not only to the dollar above the line.
The margin formula: four methods, one lesser-of rule
Margin is the heart of Chapter 171. Tex. Tax Code § 171.101 states it as a lesser-of rule, presented by the Comptroller as four methods — the entity takes the smallest:
- Total revenue times 70 percent.
- Total revenue minus cost of goods sold (COGS).
- Total revenue minus compensation.
- Total revenue minus $1 million.
Total revenue is determined from the revenue amounts reported for federal income tax, minus statutory exclusions — dividends and interest from federal obligations, Schedule C dividends, foreign royalties and dividends under IRC §§ 78 and 951–964, and certain flow-through funds. Total revenue starts from the federal return: a CPA who reconciles the federal return first has done half the work.
COGS is where service businesses get a hard lesson. It generally includes costs related to the acquisition and production of tangible personal property and real property sold in the ordinary course of business. A business that sells only services or intangibles will generally have no allowable COGS, with exceptions for certain industries. A software company with $3,000,000 of payroll has no COGS deduction to take; a distributor with $3,000,000 of product cost usually wins on the COGS method by a wide margin.
Compensation has its own rules, under § 171.1013. The deduction includes W-2 wages and cash compensation paid to officers, directors, owners, partners, and employees — including net distributive income to natural persons — subject to the inflation-adjusted per-person limit of $480,000 for 2026 and 2027. It also includes benefits provided to all personnel, such as workers' compensation, health care, and retirement benefits, to the extent deductible for federal purposes. It does not include 1099 labor or employer payroll taxes.
Margin is then apportioned to Texas using a single-factor formula based on gross receipts, under § 171.106. A company with all of its gross receipts in Texas apportions 100 percent of its margin to Texas; a company with 40 percent of its gross receipts in Texas apportions 40 percent.
The worked example: Lone Star Fabrication and the retailer next door
Take a fictional Texas manufacturer, Lone Star Fabrication LLC, an LLC taxed as a C-Corp for federal purposes. For the 2026 report year it has total revenue of $12,000,000, all of it from Texas gross receipts, COGS of $7,000,000, and compensation of $3,000,000. It is a manufacturer, not a retailer, so its rate is 0.75 percent. The four margin methods give:
- 70 percent of total revenue: 0.70 × $12,000,000 = $8,400,000.
- Total revenue minus COGS: $12,000,000 − $7,000,000 = $5,000,000.
- Total revenue minus compensation: $12,000,000 − $3,000,000 = $9,000,000.
- Total revenue minus $1,000,000: $12,000,000 − $1,000,000 = $11,000,000.
The margin is the smallest — $5,000,000, from the COGS method. Apportionment is 100 percent, so the tax is:
Now the retailer next door. Lone Star Retail LLC, also a Texas LLC, has total revenue of $3,000,000, COGS of $2,200,000, and compensation of $900,000. It buys goods and resells them, so it is primarily engaged in retail trade under the § 171.002(c) test: its retail revenue exceeds its non-retail revenue, and less than 50 percent of its retail revenue comes from products it produces. Its methods give 70 percent of $3,000,000 = $2,100,000, revenue minus COGS = $800,000, revenue minus compensation = $2,100,000, and revenue minus $1,000,000 = $2,000,000. The margin is $800,000; at the retail rate the tax is:
The retailer is above the $2,650,000 threshold for 2026, so a report is due. At $2,500,000 of revenue, no franchise tax report would be required — but the information report would still be due.
The EZ computation: when 0.331 percent wins and when it loses
Under Tex. Tax Code § 171.1016, a taxable entity whose total revenue is not more than $20 million may elect to pay the tax on apportioned total revenue at 0.331 percent, instead of computing margin at 0.375 or 0.75 percent. The EZ computation skips the margin methods entirely. For Lone Star Fabrication, the EZ tax would be $12,000,000 × 0.331 percent = $39,720 — more than the $37,500 long-form tax, because the COGS method already produced a small margin. For a service business with no COGS and thin compensation, the comparison runs the other way: a consultancy with $2,000,000 of revenue and $400,000 of compensation has margin methods of $1,400,000 at 70 percent, $1,600,000 after compensation, and $1,000,000 after the $1 million deduction — the lesser is $1,000,000, so its long-form tax at 0.75 percent is $7,500, while the EZ tax is $2,000,000 × 0.331 percent = $6,620. The EZ election saves $880 there, because the $1 million method caps the margin at half the revenue.
Who files, who does not, and the 2024 change
Historically, each taxable entity filed a franchise tax report and an information report. Effective for reports due in 2024, entities with total revenue at or below the no-tax-due threshold no longer file a franchise tax report — but they must still file an information report each year. That distinction is the single most misunderstood fact in Texas franchise tax: the information report keeps the entity in good standing, and skipping it produces the forfeiture notices.
Combined groups have a second rule: entities in an affiliated group engaged in a unitary business file a combined group report, and every member must use the same margin method, under § 171.1014 — no cherry-picking the smaller margin in each subsidiary.
Credits can reduce the tax further, and the menu changed for 2026: the research and development credit under Subchapter T and the housing development credit under Subchapter K apply to reports due on or after January 1, 2026, and the Strong Families credit under Subchapter P to reports due on or after June 1, 2026. The filing requirements for the R&D credit changed effective January 1, 2026 — the credit is not automatic.
Founder & CEO Insight — Enow A. Jovial
The calendar: May 15, extensions, and the penalty ladder
Franchise tax reports are due on May 15 each year — the next business day if May 15 falls on a weekend or legal holiday. The Comptroller will tentatively grant an extension on timely receipt of the appropriate form, meaning the request is received or postmarked on or before the due date. The extension moves the filing deadline, not the payment deadline.
The penalty ladder is short. A $50 penalty is assessed on each report filed after the due date, even when no tax is due. Tax paid 1 to 30 days late carries a 5 percent penalty; more than 30 days late, 10 percent. Interest begins 61 days after the due date. On Lone Star Fabrication's $37,500, a payment 45 days late costs:
plus interest from day 61. The fix is calendar discipline: the report is due the same day every year, and the extension form exists for the years when the books are not ready.
Final reports have their own clock. Before getting a Certificate of Account Status to terminate, convert, merge, or withdraw registration, a Texas entity must file its final tax report and pay any amount due in the year it plans to act. An out-of-state entity ending its nexus must file its final report and pay within 60 days.
Long form vs EZ vs no-tax-due: the decision table
| Situation | Best filing | Tax | Authority |
|---|---|---|---|
| Total revenue at or below $2,650,000 (2026) | Information report only | $0 | Publication 98-806 |
| Revenue under $20M, small margin | Long form at 0.375% or 0.75% | Margin × rate | Tex. Tax Code §§ 171.002, 171.101 |
| Revenue under $20M, thin deductions | EZ at 0.331% of apportioned revenue | Revenue × 0.331% | Tex. Tax Code § 171.1016 |
| Revenue over $20M | Long form only; no EZ election | Margin × rate | Tex. Tax Code § 171.1016(a) |
| Affiliated group, unitary business | Combined report; one margin method | Group margin × rate | Tex. Tax Code § 171.1014 |
| Report filed late, tax paid 45 days late | $50 + 10% + interest from day 61 | See penalty math above | Comptroller rates page |
Who should not use the EZ computation
The EZ computation is the wrong election for any entity whose margin falls below 44.13 percent of revenue — the break-even where 0.331 percent of revenue equals 0.75 percent of margin. Lone Star Fabrication's margin was 41.67 percent of revenue, so EZ lost. Any distributor or manufacturer with a real COGS deduction usually loses on EZ, and the election is unavailable above $20 million of total revenue — a growing business must re-check the threshold every year.
The filing sequence, in order
- [x] Step 1: Confirm the entity is taxable. Sole proprietorships and partnerships of natural persons are out; LLCs and corporations are in.
- [x] Step 2: Compute total revenue from the federal return, minus the § 171.1011 exclusions.
- [x] Step 3: Run all four margin methods, take the smallest, then apportion by Texas gross receipts under § 171.106.
- [x] Step 4: Price the EZ computation at 0.331 percent of apportioned total revenue and compare it with the long-form tax.
- [x] Step 5: Test the no-tax-due threshold. At or below $2,650,000 for 2026, no franchise tax report — but the information report is still due.
- [x] Step 6: File by May 15, or file the extension form on or before May 15, and pay with the report.
- [x] Step 7: Calendar the penalty ladder. A late report costs $50 even with no tax due; a late payment costs 5 percent inside 30 days, 10 percent after.
The Texas franchise tax rewards the operator who treats it as arithmetic, not as a surprise. The statute gives four margin methods and an EZ election, the Comptroller publishes the rates by report year, and the threshold tells most small businesses they owe nothing — but only if they file the information report that proves it. The Delaware franchise tax calculation guide prices the other franchise tax every founder confuses with this one, the Texas LLC vs Florida LLC formation guide covers the entity choice that creates the obligation, and the LLC dissolution playbook covers the final report. Run the numbers through the tax estimator once the margin is known.